Privacy preferences
Inderes uses cookies to provide a better user experience and a personalised service. By consenting to the use of cookies, we can develop an even better service and will be able to provide content that is interesting to you.
  • Forum
  • Premium
  • Stock Markets
    • MarketsLive prices, indices, and market performance
    • Morning ReviewDaily market recap and key overnight highlights
    • Stock CalendarUpcoming earnings, listings, and corporate events
    • Dividends CalendarFuture and past dividends
  • Companies
    • CompaniesBrowse and filter the full list of listed companies
    • DiscoveryInspiration for your next investment
    • IPOsNew listings and upcoming public offerings
    • AGM InvitationsAnnual general meeting dates and shareholder info
  • Stock Research
    • ResearchExpert stock analysis and recommendations
    • ArticlesNews, insights, and market commentary
    • PortfolioInderes model portfolio
  • Learn about investing
    • Analysis SchoolLearn how to read and understand stock analysis
    • inderesTVVideo hub for stock research, analysis, and expert commentary
    • TranscriptsFull text records of earnings calls and investor meetings
    • Stock ComparisonCompare financials and performance across multiple stocks
    • Earnings SeasonCompare EPS estimates to reported results
    • Insider TransactionsTrack buying and selling activity by company insiders
    • Short SellingSee which listed companies have disclosed short interest
    • Virtual Analyst ChatAsk questions and get instant AI-powered investment insights
    • Compound Interest CalculatorSee how your savings grow with the power of compound interest.
Find us on social media
  • Inderes Forum
  • Youtube
  • Instagram
  • Facebook
  • X (Twitter)
Get in touch
  • info@inderes.se
  • +46 8 411 43 80
  • Vattugatan 17, 5tr
    111 52 Stockholm
Inderes
  • About us
  • Our team
  • Careers
  • Inderes as an investment
  • Services for listed companies
Our platform
  • FAQ
  • Q&A
  • Terms of service
  • Privacy policy
  • Disclaimer

Inderes’ Disclaimer can be found here. Detailed information about each share actively monitored by Inderes is available on the company-specific pages on Inderes’ website. © Inderes Oyj. All rights reserved.

Scanfil Q1'25 flash comment: Successfully avoiding the worst pitfalls in a broken quarter

SCANFLAnalyst Comment2025-04-24 09:01
Antti ViljakainenHead of Research
Discuss

Translation: Original published in Finnish on 4/24/2025 at 9:10 am EEST.
Scanfil Post Q125

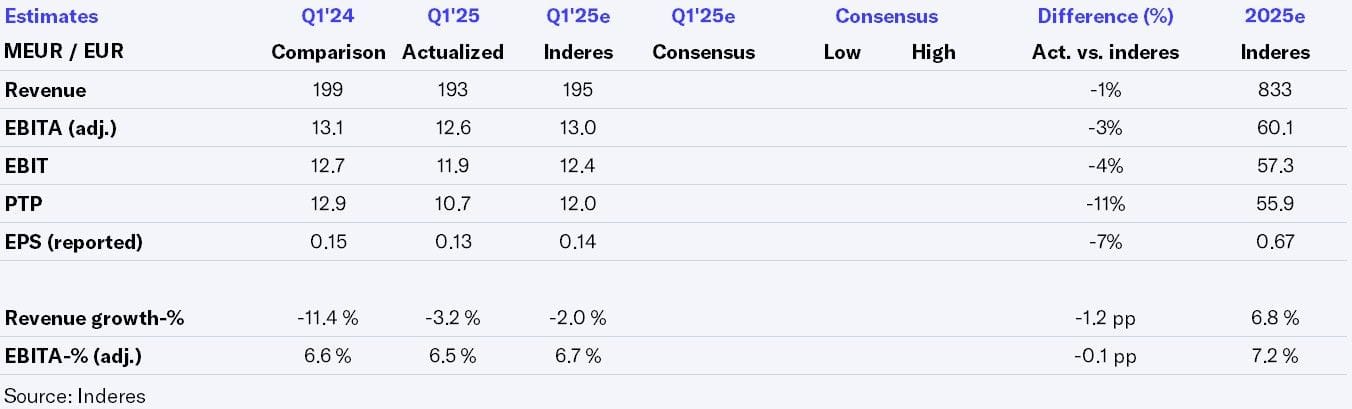
Scanfil's Q1 numbers were slightly below our estimates in a quarter dominated by the ramp-up of new projects. The company updated its earnings guidance indicator, but in practice the guidance remained unchanged, which was also in line with our expectations. Our preliminary assessment is that the report does not create significant pressure to revise our estimates for Scanfil or the consensus forecasts for the near term.

Organic contraction of revenue slowed in Q1

In Q1, Scanfil's revenue decreased by 3% to 193 MEUR from a reasonable comparison level. Organically, we estimate that revenue declined by about 7%, as the SRX acquisition supported revenue by around 4%, or 7.6 MEUR. Revenue development in the first months of the year was only slightly slower than we had forecast. The sluggish top-line development was mainly caused by sluggish demand, while the ramp-up of several new projects at various factories limited sales in the first months of the year, as previously communicated by the company. Among the company's geographic reporting segments, revenue in the Americas significantly exceeded our forecast thanks to strong demand for manufacturing services in the US, but growth in APAC was slower than expected. In Northern Europe, the decline in revenue was also slightly higher than our estimate. In Central Europe, the magnitude of the revenue decline was in line with our expectations.  

Profitability in Q1 impacted by ramp-up of won projects

Scanfil's adjusted EBITA in Q1 decreased by 4% to 12.6 MEUR, slightly below our estimates. Profitability (adj. EBITA-%) remained at a satisfactory level for Scanfil at 6.5%, as the ramp-up of projects won last year weakened the production efficiency of the factories in Q1. This was particularly evident in the Central Europe region, while in APAC the margin was burdened by the SRX acquisition. Northern Europe improved profitability from a low level, and the Americas showed strong revenue-driven earnings momentum. On the bottom line, financial expenses this time were higher than the company's normalized level and our expectations, probably mainly due to currency-based and non-cash reasons. Meanwhile, the tax rate was broadly in line with forecasts. As a result, Scanfil's Q1 EPS decreased year-on-year to EUR 0.13 per share, slightly below our forecast, reflecting in particular the operating profit and financial expenses. From a cash-flow perspective, the report was reasonable, as the seasonal working capital commitment typical for Q1 ended up being quite low.

Guidance remained virtually unchanged

Scanfil updated its approach to guidance for the current year. The company now expects a revenue of 780-920 MEUR in 2025 (unchanged), and an adjusted EBITA of 55-68 MEUR (previously adj. EBIT 53-66 MEUR). In practice, however, the guidance remained unchanged, which was also in line with our expectations. In our view, the wide ranges still reflect the uncertainty surrounding the near-term outlook, especially with regard to external factors, which have recently increased also for Scanfil due to the indirect negative repercussions of the tightening trade policy situation. However, Scanfil did not comment on the tariffs in its Q1 report. From Q2 onwards, Scanfil's growth and earnings growth will also be supported by the new projects won last year, so growth and earnings growth should pick up as long as underlying demand does not falter for macro reasons.

Scanfil is an international electronics contract manufacturer, specializing in industrial and B2B customers. Services include manufacturing of end products and components such as PCBs. Manufacturing services are the core of the company, supported by design, supply chain and modernization services. The company operates globally in Europe, America and Asia. Customers are primarily found in the process automation, energy efficiency, green efficiency and medical segments.

Read more on company page

Key Estimate Figures2025-04-09

202425e26e
Revenue779.9833.0878.1
growth-%-13.5 %6.8 %5.4 %
EBIT (adj.)53.657.361.5
EBIT-% (adj.)6.9 %6.9 %7.0 %
EPS (adj.)0.600.670.72
Dividend0.240.250.27
Dividend %2.9 %2.1 %2.3 %
P/E (adj.)13.617.616.3
EV/EBITDA7.59.68.8

Forum discussions

For Western companies selling to the Chinese market, local production is a competitive advantage that has become increasingly prominent in recent...
23 hours ago
by Pasi Hiedanpää
8
sttinfo.fi Scanfil laajentaa yhteistyötään Brukerin kanssa APAC-alueelle vastatakseen... Scanfil laajentaa yhteistyötään Brukerin Advanced X...
yesterday
by Cadel
12
Hanza, a peer company to Scanfil and Incap, published its Q3 results today, where revenue grew by 77% driven by acquisitions to SEK 2,487 million...
10/27/2026, 8:58 AM
by Tuukka Lundell
10
Antti and Tuukka have published a new company report on Scanfil following Q3 Scanfil’s Q3 figures published on Friday were operationally in ...
10/26/2026, 5:57 AM
by Sijoittaja-alokas
5
Here is Carnegie’s analysis on Scanfil following Q3 Scanfil’s Q3 report showed several encouraging signs for growth ahead, including: 1) organic...
10/24/2026, 1:15 PM
by Sijoittaja-alokas
5
Here are Antti’s and Tuukka’s quick comments on Scanfil’s Q3 results Scanfil released its Q3 report this morning. Driven by acquisitions, the...
10/23/2026, 6:26 AM
by Sijoittaja-alokas
8
And here are Scanfil’s Q3 key figures: July–September Revenue was EUR 252.2 million (191.3), an increase of 31.8% Revenue grew organically by...
10/23/2026, 5:03 AM
by Jukka
13