Inderes uses cookies to provide a better user experience and a personalised service. By consenting to the use of cookies, we can develop an even better service and will be able to provide content that is interesting to you.
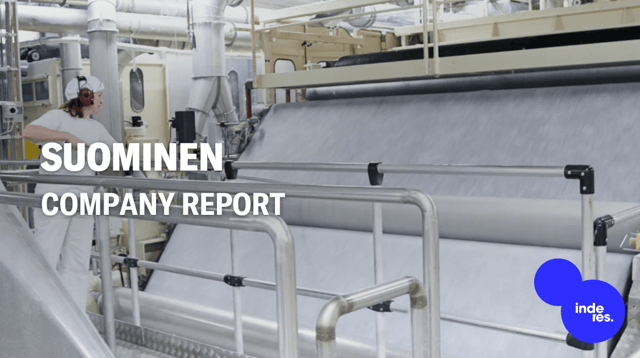
Suominen is a manufacturing company. The company manufactures and develops a wide range of wipes, hygiene products and medical applications. The manufacturing is based on non-woven fabrics that can be used for various purposes. Customers are found in several industries, with the largest operations in Europe and North America. The company has its headquarters in Helsinki.
Suominen's Q3 comparable EBITDA was slightly ahead of Vara Research consensus. The company alluded to continued operational improvements and stronger production volumes in Q3. However, we note persistent production challenges in the US that could continue...
Suominen's Q3 revenue grew by 1.3% and fell ~8% short of our estimate due to production disruptions in the US, but adjusted EBITDA (5.1 MEUR) and EBIT beat expectations. Operating cash flow turned clearly negative due to the increase in working capital. CEO Charles Héaulmé is interviewed by analyst Rauli Juva.
Join Inderes community
Don't miss out - create an account and get all the possible benefits
Inderes account
Followings and notifications on followed companies
Suominen Q2 comparable EBITDA of EUR 5.1m came 8% above Vara Research consensus expectations. Net sales of EUR 101m were up 1% y/y and came 7% below consensus. FX had EUR 1.4m posigive impact on sales. EBITDA improvement was mainly related to higher ...
Suominen's Q2 comparable EBITDA was clearly ahead of Vara Research consensus, supported by improving volumes and lower fixed costs. Self-help measures started to support development while the company noted an unfavourable mix and difficulties in meeting...
Following its rights issue, Suominen's strengthened balance sheet now allows the company to fully focus on executing its Full Potential turnaround program. However, there is still plenty of work ahead.
Suominen Q2 comparable EBITDA of EUR 4.3m came 45% above Vara Research consensus expectations. Net sales of EUR 106m were up 6% y/y and came 1% below consensus. FX had EUR 1.3m negative impact on sales. EBITDA improvement was mainly related to higher...